Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
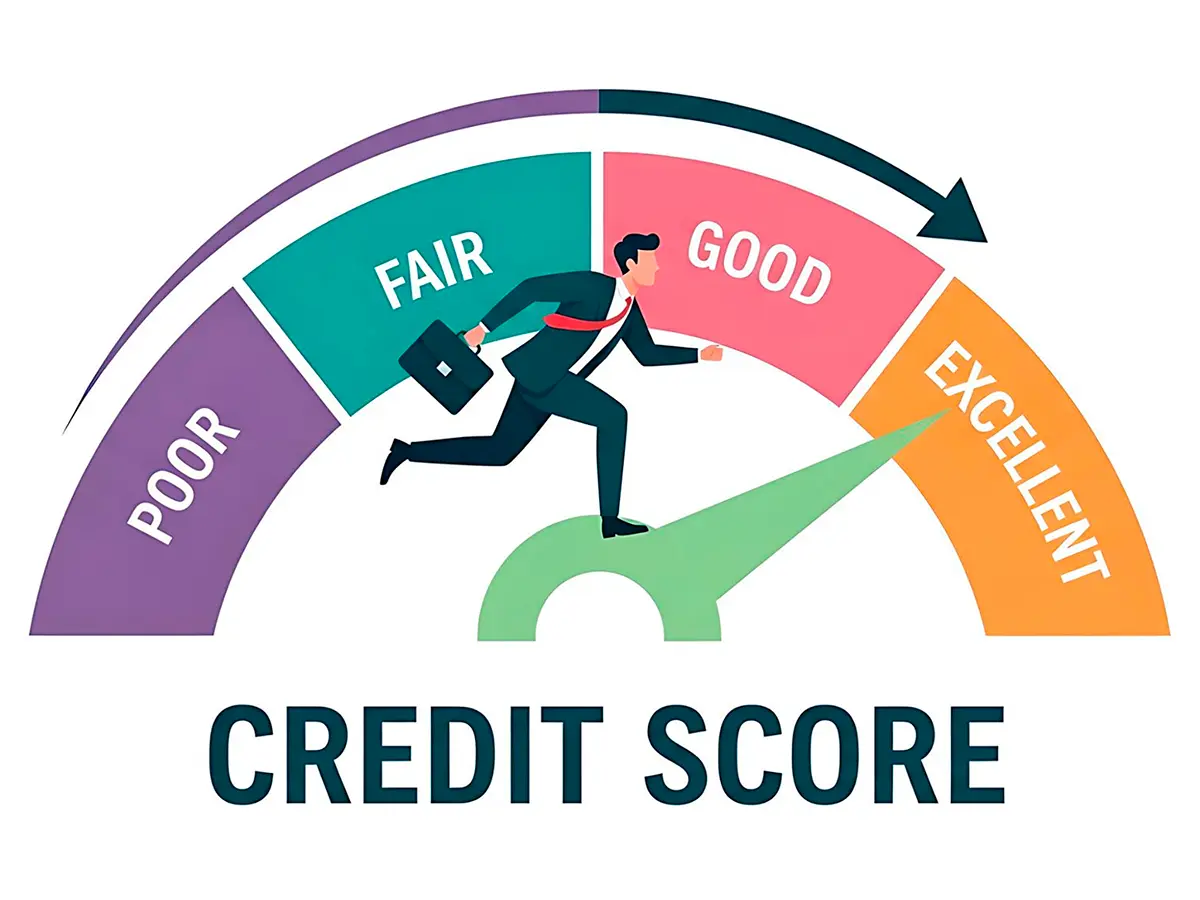
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit repair raleigh nc, made practical and calm
I'm back after a few months, focused on small, steady wins. My approach to credit repair in Raleigh feels less like a project and more like maintenance: correct what's wrong, lower what's high, automate what's easy. No drama - just progress.
Results first, because that's what matters
In four months my FICO went up 78 points, and my auto score climbed enough to trim a full percent off a preapproval. A real moment: after lunch at Morgan Street Food Hall, I sat in the car, opened my report, and filed a dispute for a telecom late that was duplicated across two bureaus. Twenty-nine days later it was corrected. That single fix moved the needle by 22 points. Not magic - just accuracy.
Convenience over complication
I kept the routine lightweight and local-friendly. Here's what actually helped without eating my weekend:
- Pull fresh reports from all three bureaus and save PDFs. I skim for duplicates, paid items showing open, and limits reported wrong. Small details add up.
- Dispute precisely: one issue per letter or online submission, with a screenshot of the tradeline and a clear ask. I track everything in a simple notes app.
- Lower utilization fast: I moved part of a balance to a local credit union promo near Hillsborough Street, kept old cards open, and made mid-cycle payments so the statement cuts lower. Utilization dropped; score followed.
- Autopay + reminders: minimums on autopay, then a calendar ping three days before each statement to push an extra payment. It's dull, which is perfect.
- Ask for goodwill (carefully): one old late with a long, otherwise clean history earned a one-time adjustment. I didn't push where I had no case.
If you want local help without the hassle
Raleigh has options you can explore when it fits:
- Nonprofit credit counseling for a quick budget tune-up or a DMP if rates are crushing you.
- Credit unions and community banks: ask which bureau they pull most often. Target cleanup where it counts.
- Repair services if you're pressed for time: look for month-to-month pricing, clear dispute logs, and check complaints with the CFPB or state AG. No big upfront fees.
What to watch so expectations stay real
- No one can remove accurate negatives. Focus on errors, balances, and on-time streaks.
- Timelines are slow on purpose: 30 - 45 days per dispute. Refile only with new evidence.
- Utilization sweet spots: under 30% overall, and ideally under 9% on at least one card.
- Mix helps, but don't force it. Don't open accounts just to "add variety."
- Pulls matter: lenders here may use any bureau - ask before you apply to avoid needless inquiries. Even some utilities and apartments do hard checks.
Quick checklist I still use
- Download all three reports and highlight anything inaccurate.
- File two clean disputes this week with proof.
- Pay $200 before the next statement on the highest-util card.
- Turn on autopay for minimums; add calendar nudges.
- Recheck reports in 35 - 45 days and log changes.
I'm not chasing perfect; I want easier approvals and lower stress. With restrained optimism and a few reliable habits, credit repair raleigh nc becomes routine rather than a rescue mission. Keep it accurate, keep it convenient, and the results show up.
Welcome to Superior Credit Care Your Path to Financial Freedom Superior Credit Care stands apart from traditional credit repair companies.
A+ Credit, Inc - Map - 4002 Barrett Dr. Ste 103. Raleigh, NC 27609. Directions - (866) 591-2769. Call Now - More Info. Hours - Known For - From the Business.
Top rated Credit Repair lawyers in Raleigh, NC - Joseph Z. Frost - Blake Y. Boyette - William H. Kroll - Raleigh, North Carolina lawyers in related practice ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.